Anthropic's Q3 Performance: Balancing Growth Ambitions with Market Realities
- Gate
- Machine Learning
- Departs
- Crew
- Azeem Azhar
- Passengers
- 429
Anthropic's recent revenue figures reveal impressive growth but also highlight challenges and market expectations that complicate its trajectory.
Anthropic has recently garnered attention following the leak of its private investor briefing, revealing significant financial figures that prompt a closer examination of the company's position within the AI industry. The reported third-quarter revenues amount to $16.8 billion, which is almost four times the company's projections for the entirety of 2025. Based on current trends, Anthropic's annualized exit revenue for Q3 could potentially reach $76 billion, showcasing the company's rapid growth rate. Notably, the information indicates a net revenue retention rate of approximately 900%, suggesting that customers are increasing their spending significantly over time.
This trajectory points toward a future where Anthropic could achieve annual revenues of $50 billion within just five years—a feat achieved by companies like Google and Meta in over a decade, and Apple and Microsoft in around 30 years. The economics behind Anthropic are becoming increasingly favorable, with the company reportedly earning $1.70 for every dollar spent on computational resources. Moreover, it recorded an adjusted gross margin of 85% despite facing fierce competition from rivals, including OpenAI, and external pressures from lower-cost providers in the industry.
Despite these impressive figures, questions linger regarding the company's ability to sustain such rapid growth. For instance, an adjusted operating margin of 11% was achieved even as Anthropic allocated 44% of its revenue toward research and development, reflecting both its commitment to innovation and the financial strains of scaling operations. The market's reaction has been muted, with significant declines in stock indices tied to the performance of AI stocks, suggesting that expectations may have been overly optimistic.
Setting Expectations and Market Reactions
The context behind these numbers is critical. Anthropic's Q2 performance set high expectations, with prior leaks suggesting an annual revenue projection of $65 billion. A series of successful product innovations—including Claude Code and Opus models—had propelled the company beyond its initial financial forecasts, leading to what may have been an inflated perception of its growth trajectory. However, the third-quarter results signal a possible reversion to mean performance levels, which has left investors questioning the sustainability of the growth rates previously witnessed.
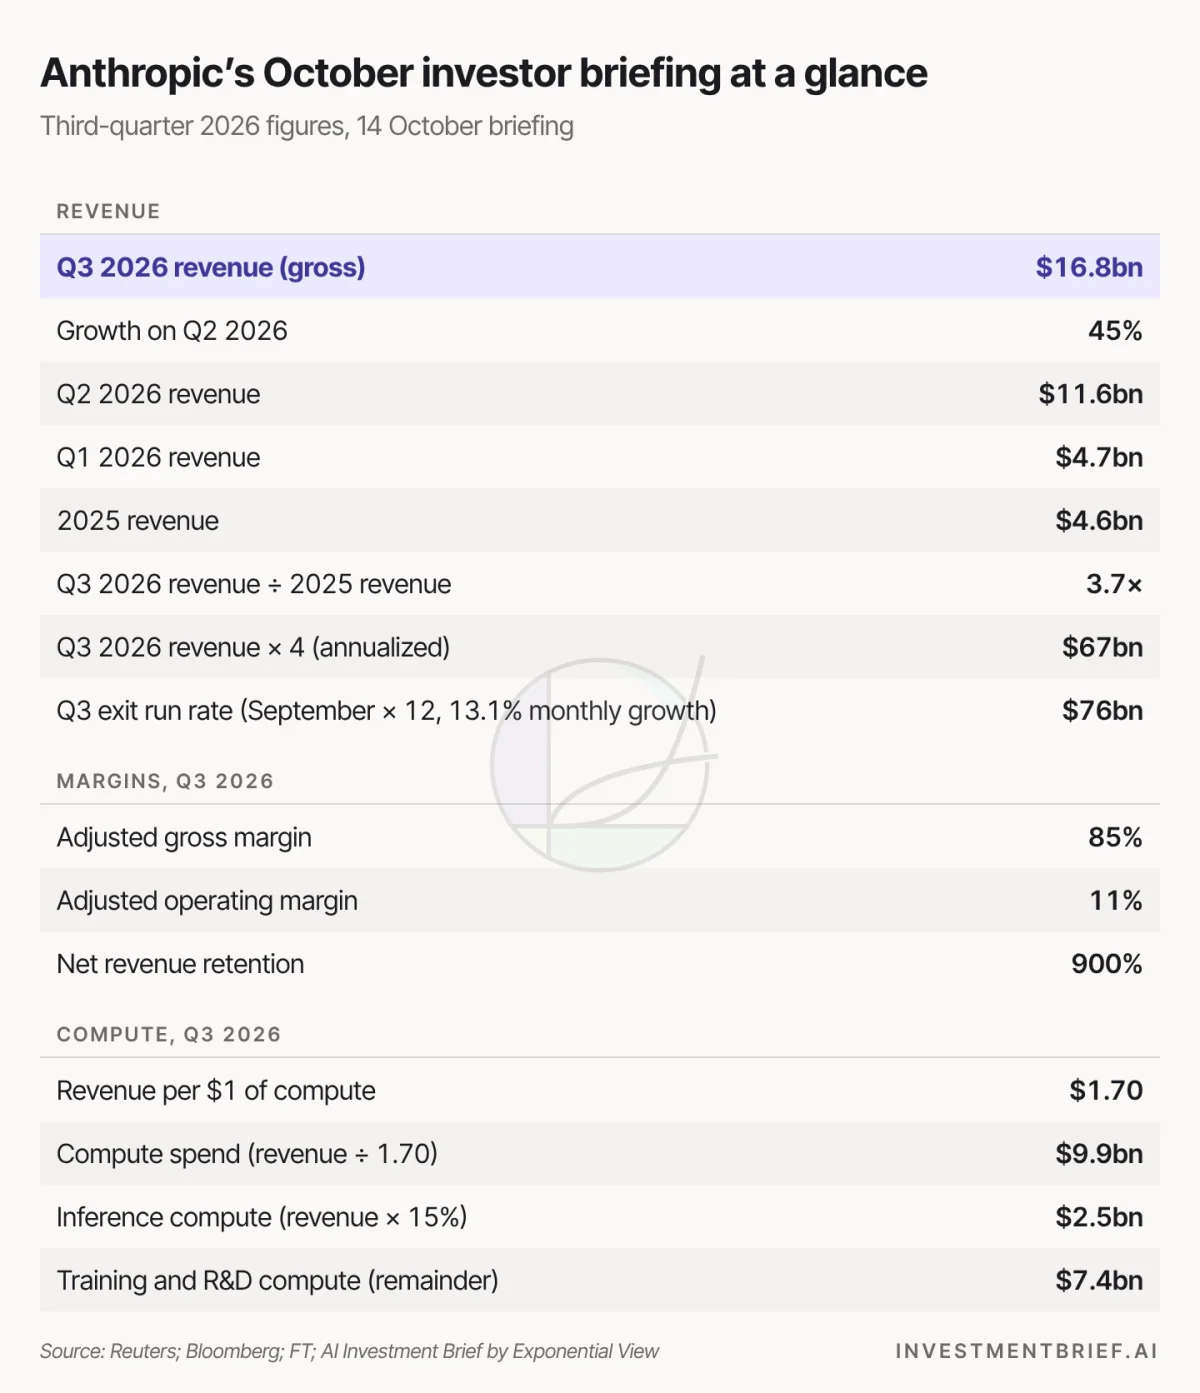
Comparatively, the year-on-year growth rate for Q3 stands at about 1,000%. The growth from Q2 to Q3 is a still-healthy 45%, but this marks a significant deceleration from the 147% increase seen between Q1 and Q2. The lingering concern is whether this is a natural adjustment or indicative of deeper issues within the company’s growth engine. Investors now face a crucial question: is the Q2 performance the outlier, indicative of an early surge, while Q3 represents a norm settling into play? Or are the struggles in Q3 symptomatic of broader competitive dynamics at work within the AI sector?
Future Projections and Strategic Implications
Looking ahead, Anthropic aims to reach $60 billion in revenue for the full year, necessitating an extraordinary performance of $26.9 billion in Q4—a target requiring 60% growth quarter on quarter. Achieving this would require not just sustaining existing momentum through the end of the year but also successfully converting more customers into higher spenders. Considering the tangible decline in growth rates, the company faces formidable obstacles in reaching this ambitious goal.
While Anthropic has a healthy annualized growth rate of around 340%, the critical question will be the sustainability of this growth over the next two to three years. Understanding how quickly this growth might taper off will be vital for assessing the long-term viability of the company's business model. A gradual tapering could indicate continued strength in its market position, while a more abrupt decline could prompt further scrutiny of its operational strategy.
Overall, the recent financial disclosures from Anthropic offer a mixed picture. While the company is certainly on a growth trajectory with substantial revenues, the challenges and market expectations they face cannot be overlooked. Investors and analysts alike will be closely monitoring Anthropic's subsequent steps as the company positions itself in a highly competitive landscape.
The forthcoming S-1 filing will shed further light on how Anthropic envisions its path forward and whether it can truly navigate the hurdles that lie ahead. Only then will a clearer picture of its market potential and operational resilience emerge.


